
Credit Repair Services: Stop Paying for Past Credit Mistakes
A credit mistake can take minutes to make but influence your finances long after the moment has passed. Credit repair services can help you examine potentially inaccurate or questionable credit reporting, understand what is still affecting your profile, and develop a more deliberate strategy for moving forward.
The real cost of damaged credit is not simply a lower score. It can appear in financing decisions, borrowing costs, available credit, and—especially for entrepreneurs—the financial flexibility needed to pursue the next opportunity.
In This Guide You’ll Learn
- How past credit problems can continue creating financial friction today
- Which credit issues may deserve attention and which require a different strategy
- How to turn credit recovery into preparation for personal and business growth
Table of Contents
- The Mistake May Be Over, but the Cost May Not Be
- What Credit Repair Services Actually Do
- The Hidden Price of Damaged Credit
- Why One Credit Mistake Can Have a Long Financial Tail
- First Question: Is the Information Accurate?
- Not Every Negative Item Is a Credit Repair Problem
- Start With the Three-Bureau Picture
- The Credit Mistakes Worth Investigating
- Stop the Financial Bleeding Before Chasing a Score
- Credit Repair Services vs. Credit Rebuilding
- Why Credit Utilization Can Keep You Stuck
- When Old Debt Collides With New Business Goals
- The Entrepreneur’s Credit Readiness Test
- Separate Personal Credit Problems From Business Problems
- Before Applying for Business Funding, Do This First
- What Legitimate Credit Repair Cannot Promise
- How to Choose Credit Repair Services Without Getting Burned
- Build a Credit Comeback With a Destination
- Your Next 90 Days: Repair, Rebuild, Prepare
- People Also Ask
The Mistake May Be Over, but the Cost May Not Be
Maybe you missed payments during a difficult year.
Maybe a credit card balance became bigger than expected.
Perhaps a vehicle was repossessed, an account went to collections, or you simply did not understand credit when you first started using it.
The event happened in the past.
But then you apply for something today.
Suddenly, yesterday is back in the room.
That is what makes damaged credit so frustrating. The original financial problem may be finished, yet information associated with it can continue influencing your financial options while it remains part of your credit history.
For entrepreneurs, that friction can arrive at an especially inconvenient time. You may finally have the idea, customers, business plan, or opportunity—but your personal financial profile has not caught up with your ambition.
That is why the smartest question is not:
How do I erase my past?
It is:
How do I stop allowing past credit problems to dictate my next financial decision?
That is a much more useful place to begin.
What Credit Repair Services Actually Do
Credit repair services help consumers review their credit information, identify potentially inaccurate, incomplete, outdated, or otherwise disputable reporting, and take appropriate steps to challenge legitimate issues.
Professional help can be valuable when reports are complicated or when you are unsure what deserves attention.
A reputable credit repair service should not sell fantasy.
It should provide clarity.
That distinction matters because accurate negative information generally cannot simply be removed because it is inconvenient or hurting a score.
Instead, effective credit repair starts by separating three things:
- What may be reported incorrectly
- What is accurate but financially damaging
- What behavior needs to change going forward
Each requires a different response.
A negative item and an inaccurate item are not automatically the same thing. The objective is not to dispute everything negative. It is to identify what may legitimately need correction while improving the financial factors within your control.
The Hidden Price of Damaged Credit
People tend to measure bad credit in points.
- 620. 650.
But points do not tell the entire story.
The more consequential question is:
What is your current credit profile costing you?
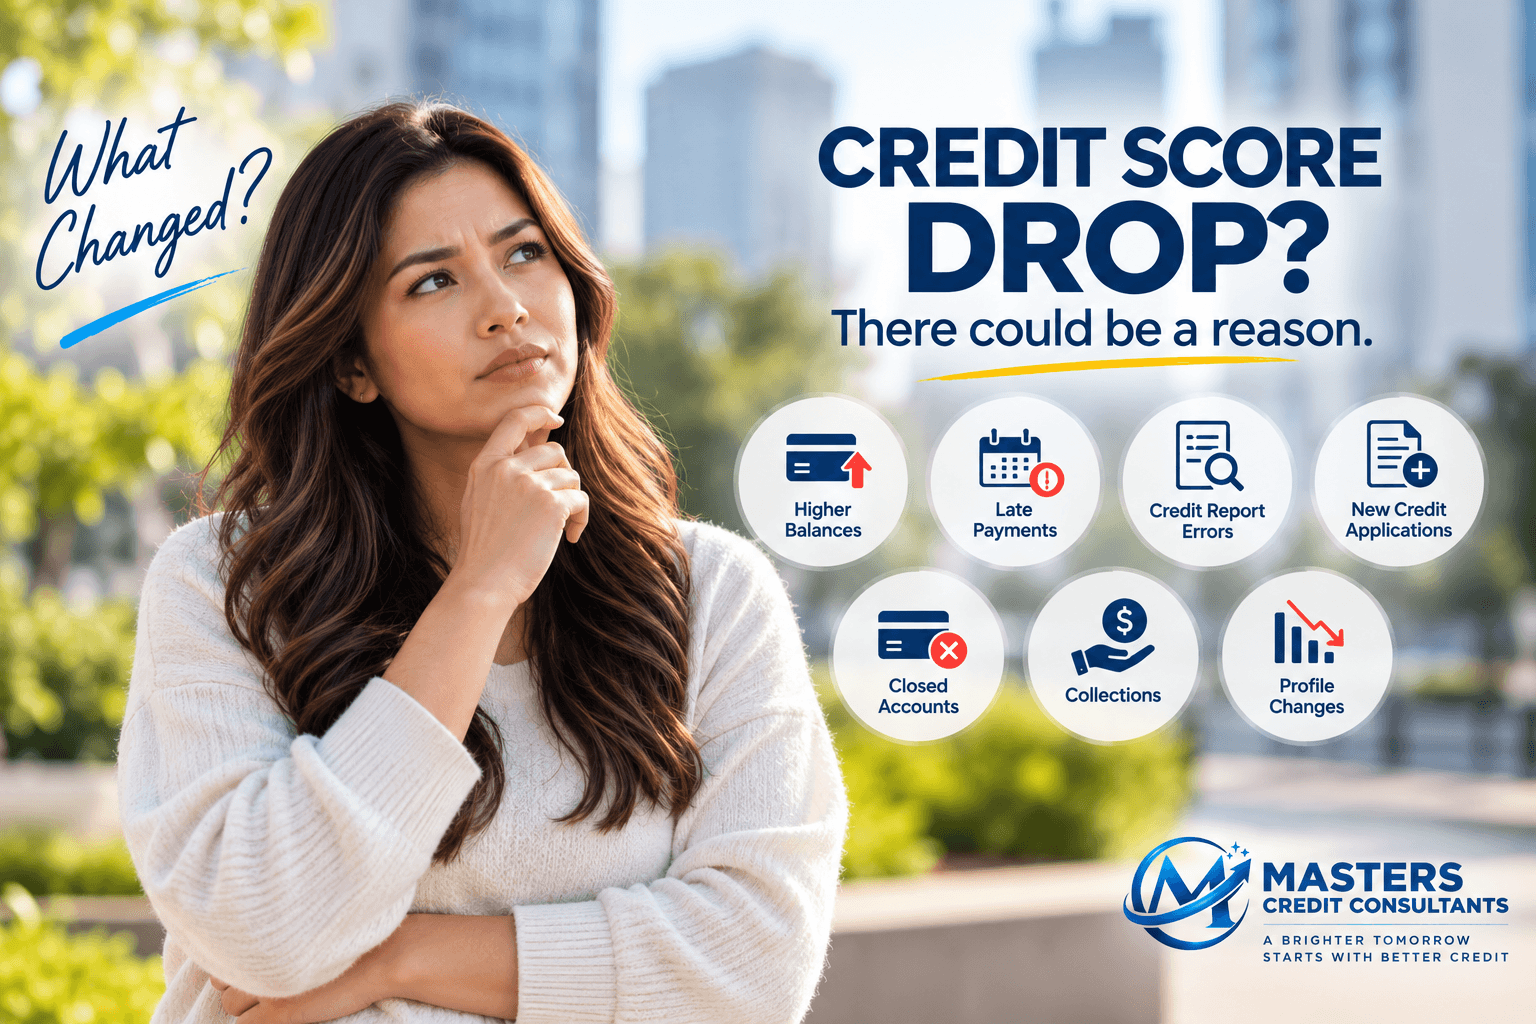
Depending on the transaction, lender, insurer, landlord, jurisdiction, and other factors, weaker credit can contribute to financial friction such as:
- Fewer financing options
- Less favorable borrowing terms
- Higher interest costs
- Lower available credit limits
- Larger security deposits in some situations
- Difficulty qualifying for certain apartments
- Challenges obtaining some forms of business financing
- Reduced flexibility when unexpected expenses occur
Consider borrowing costs.
A borrower receiving a less favorable interest rate may pay considerably more over the life of a large loan than someone who qualifies for stronger terms.
That is money leaving your pocket because of financing conditions—not because the underlying purchase became more valuable.
The cost can become even more consequential for business owners.
Capital has a price.
When your financing choices narrow, the cost of accessing capital can increase—or capital may simply become unavailable through the channel you wanted to use.
Do not evaluate your credit only by asking, “What is my score?” Ask, “What opportunities or dollars might my current credit profile be costing me?”
That question changes the conversation.
Why One Credit Mistake Can Have a Long Financial Tail
Financial decisions can develop what might be called a long financial tail.
The original event ends.
Its consequences continue.
A missed payment, charged-off account, collection, repossession, or other negative history may continue appearing according to applicable credit-reporting rules and circumstances.
Meanwhile, life moves forward.
You want another vehicle.
You start earning more.
You launch a company.
You want to buy a home.
The frustrating part is the temporal mismatch: your financial situation today may be completely different from the circumstances surrounding the original mistake.
But credit decisions are often based partly on documented history.
That is why recovery requires two parallel efforts:
Correct legitimate reporting problems.
And:
Create stronger new financial evidence.
You cannot rewrite yesterday.
You can influence what happens next.
First Question: Is the Information Accurate?
Before attempting to “fix” any negative credit item, ask the most important question in credit repair:
Is it accurate?
Suppose a credit report lists an account as late.
If you actually paid on time, you may have a reporting problem worth investigating.
If the payment really was late, the problem is different.
Likewise, an account may deserve closer examination when:
- It does not belong to you
- The balance appears incorrect
- The payment history seems wrong
- The same obligation appears duplicated
- An account status appears inaccurate
- Information associated with identity theft appears
- Account details do not match your records
This distinction keeps your strategy legitimate and focused.
Credit repair is not a contest to see how many negative items can be disputed.
It is an exercise in accuracy.
Not Every Negative Item Is a Credit Repair Problem
This is where many credit-repair strategies become muddled.
Imagine someone has five problems:
- A potentially inaccurate collection
- A legitimate late payment
- High revolving balances
- An unfamiliar account
- Three recent credit applications
All five may affect the overall financial picture.
But they are not five versions of the same problem.
The questionable collection may warrant investigation.
The late payment may require time and stronger future payment behavior.
High revolving balances may require a repayment strategy.
The unfamiliar account may raise identity-theft concerns.
The recent applications may suggest that another application is exactly what you should not do next.
Different problem.
Different tool.
Different response.
Stop asking, “How do I remove everything bad?”
Start asking, “What category does each problem belong to, and what is the appropriate response?”
That is a more sophisticated approach to credit recovery.
Start With the Three-Bureau Picture
You cannot make an informed credit strategy based on assumptions.
Begin by reviewing your credit information.
For consumers who want access to credit reports, scores, and ongoing monitoring, IdentityIQ offers the following promotional option:
IdentityIQ $1 (7-day Trial)
Access the IdentityIQ $1 7-Day Trial
Features advertised with the offer include:
- Experian, Equifax and TransUnion™ Reports & Scores Can Be Refreshed Every 30 Days
- 3 Bureau Daily Monitoring & Alerts
- Dark Web Monitoring
- $1,000,000 Identity Theft Insurance
IdentityIQ is a third-party service. Features, eligibility, insurance terms, promotional pricing, renewal pricing, and other conditions may change. Review the current offer and terms before enrolling.
Once you have access to your reports, resist the temptation to stare only at the scores.
A score is an output.
The report contains the underlying information.
Review:
- Personal identifying information
- Open accounts
- Closed accounts
- Balances
- Payment histories
- Collection accounts
- Account statuses
- Credit inquiries
- Accounts you do not recognize
- Information that conflicts with your own records
Think like an auditor rather than a panicked borrower.
Observe first.
Act second.
The Credit Mistakes Worth Investigating
Some credit problems deserve closer scrutiny because the information itself may be questionable.
Potential examples can include:
- An account that is not yours
- Incorrect balances
- Incorrect payment statuses
- Duplicate reporting
- Payments incorrectly shown as late
- Accounts with inaccurate identifying details
- Potential identity-theft-related accounts
- Incorrect collection information
- Accounts that were not properly updated after a change
- Repossession details that appear inconsistent with your records
Finding something suspicious does not automatically mean it will be deleted.
It means you have identified something worth examining.
Gather documentation where available.
Compare dates.
Compare balances.
Review correspondence.
Look for discrepancies.
Precision is more useful than indiscriminate disputes.
Stop the Financial Bleeding Before Chasing a Score
Here is an uncomfortable scenario.
Someone spends months trying to repair old credit while creating new late payments.
That is like repairing the roof while leaving the faucet running upstairs.
Before obsessing over points, stabilize the present.
Where financially possible, priorities may include:
- Keeping current obligations current
- Avoiding unnecessary new debt
- Creating a workable monthly budget
- Developing a plan for high revolving balances
- Establishing payment reminders or autopay
- Building a modest emergency reserve
- Monitoring accounts for suspicious activity
Credit repair should not become a distraction from financial management.
The strongest comeback combines both.
Before asking what you can remove from yesterday, make sure you are not creating another problem today.
Credit Repair Services vs. Credit Rebuilding
These terms are often used interchangeably, but separating them can make your strategy clearer.
Credit repair generally focuses on identifying and addressing potentially inaccurate or disputable information in your credit files.
Credit rebuilding focuses on the financial behaviors and credit-management decisions that create stronger history moving forward.
You may need one.
You may need both.
For example, correcting an inaccurate late payment may address a reporting issue.
Paying future obligations on time is rebuilding.
Correcting an inaccurate balance is repair.
Reducing legitimately high revolving debt is financial management and rebuilding.
The distinction prevents unrealistic expectations.
A credit repair company can assist with appropriate credit-report issues.
It cannot make financial decisions for you every month.
Why Credit Utilization Can Keep You Stuck
You can have perfect intentions and still carry a financial profile that looks stretched.
Credit utilization generally describes how much revolving credit you are using relative to your available revolving limits.
For example, if a card has a $5,000 limit and a $4,000 reported balance, its utilization is 80%.
High revolving utilization can affect commonly used credit-scoring models.
More importantly, consistently carrying large balances can make your finances brittle.
One emergency can become another credit-card charge.
Then another.
Soon, the credit problem is not an isolated event from years ago. It is an active cash-flow problem.
If reducing balances is financially realistic, build a deliberate repayment plan instead of chasing arbitrary hacks.
Sustainable beats theatrical.
When Old Debt Collides With New Business Goals
Now imagine this:
You have spent two years building a side business.
Customers are arriving.
You are ready for equipment, inventory, advertising, staff, or a larger location.
You need capital.
This is where personal credit and entrepreneurship can unexpectedly collide.
Depending on the lender, financing product, business history, and underwriting standards, personal credit may be one factor considered—particularly when the company is relatively young.
Your old credit problem has suddenly become a business-planning problem.
This does not mean a higher credit score automatically unlocks business financing.
Far from it.
Business lenders may also examine:
- Revenue
- Cash flow
- Time in business
- Existing debt
- Industry
- Business credit
- Banking activity
- Collateral
- Financial statements
- Guarantees
- Other underwriting criteria
Credit is one component of a larger funding profile.
That is precisely why entrepreneurs should address it before funding becomes urgent.
The Entrepreneur’s Credit Readiness Test
Before applying for business financing, run a readiness test.
Ask yourself:
Do I know what is currently on my personal credit reports?
Have I investigated potentially inaccurate information?
Are my revolving balances manageable?
Am I current on existing obligations?
Do I understand my business cash flow?
Are my personal and business finances appropriately separated?
Do I have organized financial records?
Do I know what type of financing I actually need?
Have I researched qualification requirements before applying?
If several answers are “no,” your next step may not be another application.
It may be preparation.
Funding readiness begins before the application. Strong entrepreneurs prepare their financial profile, business records, cash flow story, and capital requirements before asking a lender for money.
If your credit and business plans are becoming intertwined, a free consultation with Masters Credit Consultants can help you discuss your current credit position and broader goals before deciding on your next move.
Separate Personal Credit Problems From Business Problems
A common entrepreneurial mistake is treating the business bank account like a second personal checking account.
Money moves back and forth.
Personal expenses appear alongside business expenses.
Receipts disappear.
Bookkeeping becomes archaeology.
Then the owner wants funding.
Even excellent personal credit cannot compensate for every weakness in a business.
Proper organization matters.
Depending on your situation, strengthening the business foundation may involve:
- Choosing an appropriate legal structure
- Maintaining dedicated business banking
- Keeping accurate bookkeeping records
- Tracking revenue and expenses
- Monitoring cash flow
- Understanding tax responsibilities
- Building appropriate business credit relationships
- Maintaining financial statements
- Documenting owner contributions and withdrawals
Business structure can have legal, tax, financial, and operational consequences. Choose a structure based on your actual circumstances and seek qualified legal or tax advice where necessary—not solely because a social-media video claims one entity type unlocks funding.
A business should be structured to function properly.
Not simply to look fundable.
Before Applying for Business Funding, Do This First
The worst time to discover a credit problem is after submitting an important financing application.
Preparation gives you time to react intelligently.
Before pursuing funding:
Review your personal financial profile.
Know what a lender may potentially see where personal credit is relevant.
Review your business numbers.
Know your revenue, expenses, cash flow, and existing obligations.
Define the use of funds.
“I need money for my business” is not a strategy.
Know approximately how much capital you need, what it will finance, and how the business expects to support repayment.
Research the financing product.
A credit card, line of credit, equipment loan, term loan, invoice financing arrangement, and other financing structures solve different problems.
Avoid application roulette.
Submitting applications indiscriminately can create unnecessary inquiries and may result in financing that does not fit your business.
Preparation is less exciting than approval.
It is also what makes responsible approval more useful.
What Legitimate Credit Repair Cannot Promise
Credit repair advertising can become noisy.
Fast results.
Huge score jumps.
Guaranteed deletions.
Clean credit.
Start over.
Be skeptical.
A legitimate credit repair service cannot responsibly guarantee:
- A specific credit score
- A particular point increase
- Removal of every negative item
- Deletion of accurate information merely because it is damaging
- Guaranteed loan approval
- Guaranteed business funding
- A universal completion date
Credit outcomes depend on the information in an individual’s files, investigation results, ongoing financial activity, scoring models, and other variables outside any credit repair company’s control.
Promises should make you cautious.
Process should make you interested.
How to Choose Credit Repair Services Without Getting Burned
When evaluating a provider, ignore the dramatic testimonials for a moment.
Ask practical questions.
What exactly are you paying for?
How does the company review your credit?
How are potential inaccuracies identified?
How will you receive progress updates?
What are the fees?
What are the cancellation terms?
What educational support is included?
What happens if an item is verified?
Does the company make promises it cannot control?
Be particularly cautious if someone encourages you to:
- Dispute information you know is accurate
- Misrepresent your identity
- Apply for credit using false information
- Create a so-called new credit identity
- Conceal relevant information from lenders
- Pay based on unrealistic guaranteed outcomes
A trustworthy company should help make credit less mysterious.
At Masters Credit Consultants, the broader objective is to help consumers and entrepreneurs understand their credit position and develop a strategy for moving forward—not simply chase a number without context.
Build a Credit Comeback With a Destination
Why do you want better credit?
Seriously.
Write down the answer.
I want to buy a house.
I want a reliable vehicle.
I want to stop paying unnecessarily expensive borrowing costs.
I want to start a business.
I want to prepare for business funding.
I want more financial flexibility.
Now your credit strategy has a destination.
Without a destination, people often become obsessed with tiny score fluctuations.
Up five points.
Down seven.
Up twelve.
Panic.
Refresh.
Repeat.
That is not financial planning.
The objective is to create a credit profile and broader financial position capable of supporting what you want to do next.
Do not build credit simply to admire your score. Build a stronger financial profile so you are better prepared when a meaningful opportunity arrives.
Why Credit Education Matters
One of the biggest mistakes people make is viewing credit repair as a temporary fix.
Removing or correcting inaccurate information doesn’t automatically prevent future credit problems.
Understanding how credit works helps you make better decisions about:
- Credit cards
- Payment schedules
- Account balances
- Financing
- Debt
- New credit applications
- Credit monitoring
- Long-term financial planning
The ultimate goal shouldn’t simply be a different number on your credit report.
It should be creating a stronger financial foundation.
Your Next 90 Days: Repair, Rebuild, Prepare
Credit recovery becomes less intimidating when you divide it into manageable phases.
Days 1–30: Investigate
Review your credit information.
Document questionable reporting.
List outstanding obligations.
Calculate monthly debt payments.
Review revolving balances.
Identify upcoming financial goals.
Do not rush into another application.
Understand first.
Days 31–60: Stabilize
Address legitimate credit-reporting issues.
Keep current accounts current.
Create a repayment strategy where appropriate.
Reduce avoidable spending.
Avoid unnecessary applications.
Start creating a financial buffer if possible.
Days 61–90: Prepare
Review changes.
Continue responsible payment behavior.
Reassess balances.
If entrepreneurship is your goal, organize business banking, bookkeeping, revenue records, cash-flow information, and funding requirements.
Then ask one final question:
Am I in a stronger position than I was 90 days ago?
Not perfect.
Stronger.
That is progress.
People Also Ask About Credit Fixing Services
Can credit repair services remove past credit mistakes?
Credit repair services can help identify and dispute credit information believed to be inaccurate, incomplete, or otherwise disputable. They cannot legitimately guarantee removal of accurate negative information. The outcome depends on the specific reporting, documentation, investigation, and applicable credit-reporting requirements.
Can bad personal credit prevent me from getting business funding?
Personal credit can influence certain business financing decisions, particularly when the business is new or a personal guarantee is involved. However, lenders may also consider revenue, cash flow, time in business, debt, industry, business credit, collateral, and other underwriting criteria. A credit score is only part of funding readiness.
How can an entrepreneur rebuild credit before applying for funding?
Start by reviewing credit information for potential inaccuracies, keeping current obligations on time, managing revolving balances, and avoiding unnecessary applications. At the same time, strengthen the business by separating finances, maintaining accurate bookkeeping, monitoring cash flow, and researching lender requirements before submitting financing applications.
Stop Letting Yesterday Finance Tomorrow
Past financial mistakes deserve perspective.
Learn from them.
Address legitimate reporting problems.
Change what needs changing.
But do not allow yesterday’s decisions to become tomorrow’s permanent financial strategy.
Professional credit repair services may help you identify potentially inaccurate information and navigate appropriate credit-report issues. The bigger opportunity, however, is using that process as the beginning of a stronger financial system.
For entrepreneurs, that system matters even more.
Masters Credit Consultants is a trusted credit repair company focused on helping consumers and entrepreneurs better understand their credit needs, address legitimate credit-reporting issues, repair their credit score where appropriate, and build stronger strategies for the future.
For business owners, the conversation can extend beyond credit repair.
It can mean preparing to start a business, structuring businesses properly, improving business strategy, strengthening financial readiness, and preparing for growth opportunities.
If your goal is to improve your credit score fast, remember that legitimate credit improvement does not come with guaranteed timelines or predetermined score increases. A better objective is to make smart, targeted moves that address the factors affecting your individual credit profile.
Your mistake happened yesterday.
Your strategy begins today.
Do not keep paying for the past longer than necessary.
🚀 Schedule Your Free Credit Consultation with Masters Credit Consultants
Schedule a free consultation with Masters Credit Consultants and discover how a personalized credit improvement strategy can help you achieve your financial goals.
Whether you’re preparing to buy a home, qualify for better financing, rebuild after financial hardship, or strengthen your business opportunities, taking action today could open the door to greater possibilities tomorrow.
📞 Phone: 1-844-620-8796
🌐 Website: https://www.masterscredit.com
📅 Schedule Your Free Consultation:
https://www.masterscredit.com/sign-up/
Additional Helpful Links
- Credit Fixing Services: A Guide to Improving Your Credit
- Credit Repair Houston: A Smarter Guide to Rebuilding Your Credit and Unlocking Better Financial Opportunities
- Credit Repair Near Me When DIY Isn’t Working? Here’s What to Do
- Credit Repair Specialist Solutions for Financial Freedom
Related Questions
-
Can credit repair services remove past credit mistakes?
-
How long do negative items stay on your credit report?
- Can old credit mistakes still lower your credit score?
- Is it possible to fix bad credit from years ago?
- What credit mistakes can be disputed or corrected?
- How fast can credit repair improve your credit score?

Leave A Comment