
Why Did My Credit Score Drop? 7 Common Reasons to Check
Seeing your credit score suddenly drop can be concerning, especially when you’re not sure what changed.
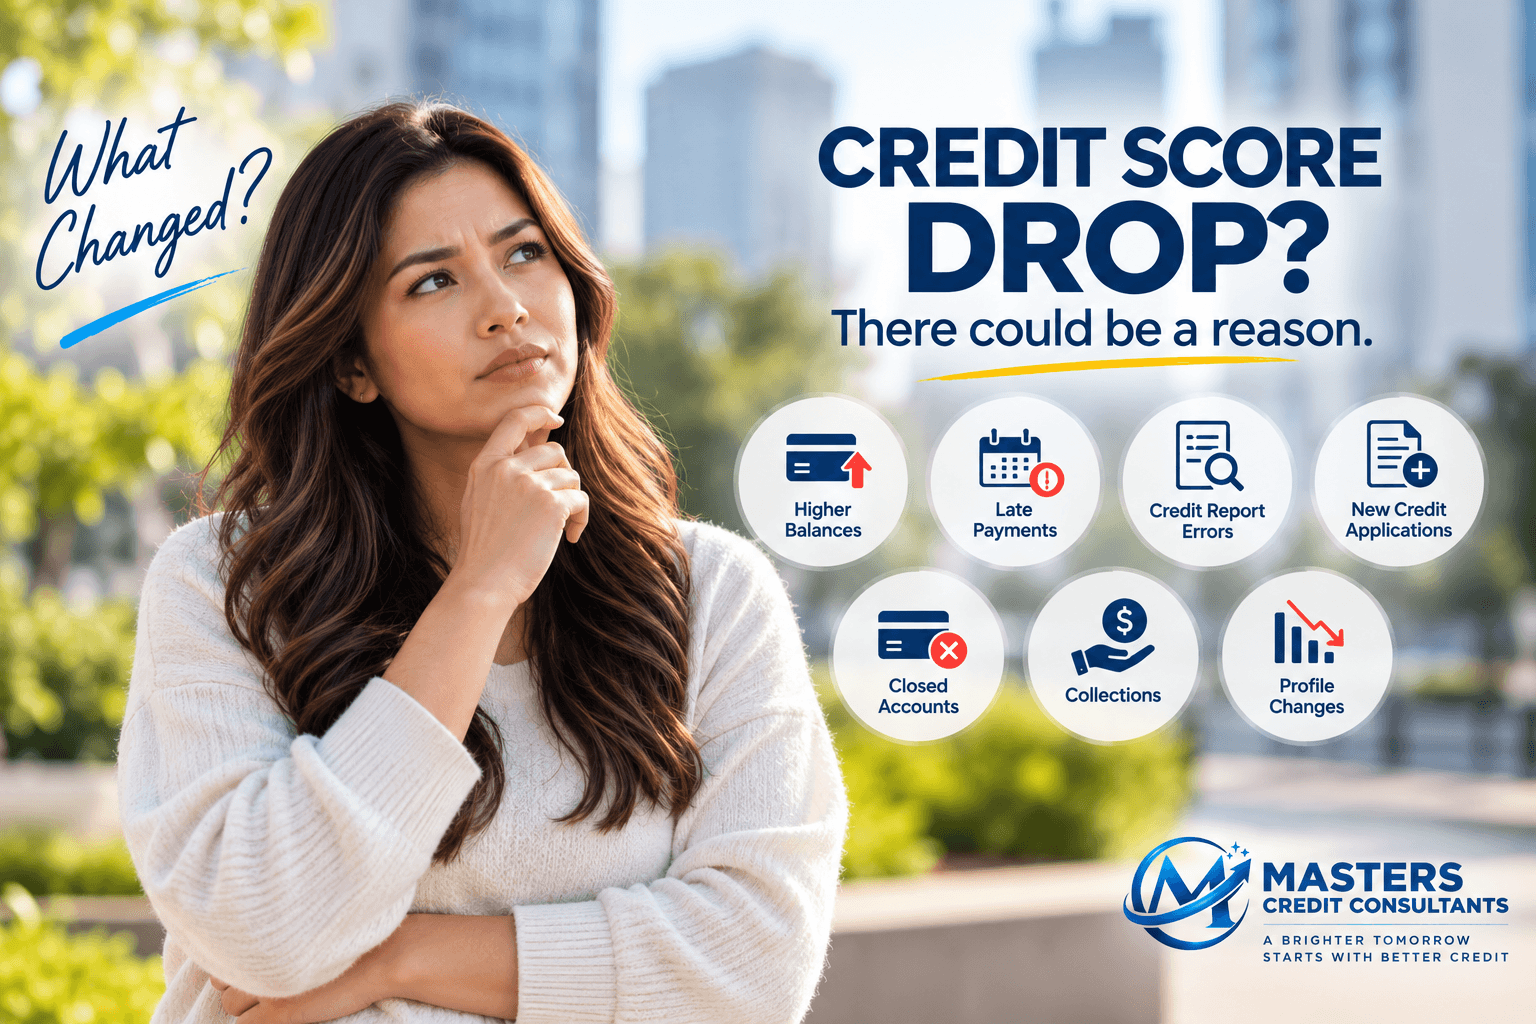
A lower credit score doesn’t always mean you’ve done something dramatically wrong. Changes to your reported credit card balances, payment history, new credit applications, account information, or potential credit report errors may all play a role.
If you’re working on credit repair or trying to improve your credit, the first step is understanding what changed in your credit profile rather than assuming you need a quick fix.
Three Things to Know
- A credit score can change when information in your credit reports changes.
- A drop doesn’t automatically mean there is an error.
- Reviewing your credit reports can help you identify whether you need better credit habits or assistance from a credit repair company.
1. Your Credit Card Balances Increased
Higher credit card balances can increase your credit utilization ratio, which compares your reported revolving balances with your available credit limits.
For example, if you have a $5,000 credit limit and your reported balance increases from $500 to $2,500, your utilization rises from 10% to 50%.
Even if you haven’t missed a payment, a significant increase in utilization may affect your credit score.
Paying down revolving balances can lower your utilization after updated balances are reported, although this doesn’t guarantee a specific score increase.
1. Look for Credit Report Errors
Don’t assume everything appearing on your credit report is correct.
Potential errors can include:
- Accounts that aren’t yours
- Incorrect balances
- Payments incorrectly reported as late
- Duplicate account information
- Incorrect account status
- Accounts potentially resulting from identity theft
Finding negative information doesn’t automatically mean you need credit repair.
The key question is whether the information is being reported accurately.
If you believe information is inaccurate or incomplete, it may be appropriate to investigate and dispute it.
2. A Payment Was Reported Late
Payment history is an important part of your credit profile.
If a payment is reported late, it may negatively affect your credit. That’s why it’s important to check whether the late payment is accurate.
If you paid on time but your credit report shows otherwise, the information may deserve further investigation.
This is one situation where credit repair services may help consumers review potentially inaccurate reporting and determine what steps may be appropriate.
3. You Applied for New Credit
Applying for a new credit card or loan may result in a hard inquiry appearing on your credit report.
One inquiry doesn’t necessarily mean serious credit trouble, but multiple applications within a short period can affect your overall credit profile.
Before applying for additional credit, consider whether you actually need the new account. Applying for several accounts simply because your score dropped may create additional changes to your credit profile.
4. You Closed a Credit Card
Closing a credit card may reduce your total available revolving credit.
Suppose you owe $2,000 across credit cards with combined limits of $10,000. Your overall utilization is 20%.
If you close an unused card and your combined available limits fall to $5,000 while your balances remain $2,000, your utilization becomes 40%.
That’s why closing an account can sometimes affect your credit even when you haven’t taken on additional debt.
Before closing an older or unused account, consider how the change could affect your available credit and overall credit profile.
5. A Collection or Other Negative Account Appeared
A newly reported collection, charge-off, or other negative account may be another reason for a credit score change.
Don’t immediately assume that credit repair can remove the negative item.
First, determine whether the account and reported information are accurate.
Check the account details carefully, including the creditor, balance, payment history, and whether you recognize the debt.
If something appears incorrect, incomplete, or unfamiliar, you may have grounds to investigate the information further and determine whether a dispute is appropriate.
6. There May Be an Error on Your Credit Report
Credit reports can contain inaccurate or incomplete information.
Potential credit report errors might include:
- An account that doesn’t belong to you
- An incorrect balance
- Incorrect payment history
- Duplicate account information
- An account incorrectly shown as open or past due
- Information potentially connected to identity theft
This is where legitimate credit repair differs from promises to simply “erase bad credit.”
A professional credit repair company can help you review your reports and identify potentially inaccurate or questionable information. However, accurate negative information generally cannot be removed simply because it negatively affects your credit.
If you’re reviewing your credit reports to understand why your score changed, Masters Credit Consultants recommends obtaining a copy of your 3-bureau credit report through IdentityIQ’s $1 7-Day Trial, which provides access to your credit reports, scores, monitoring alerts, and identity theft protection.
Start Here – IdentityIQ $1 7-Day Trial
Reviewing information from all three bureaus can make it easier to compare what is being reported and identify information that may need a closer look.
7. Your Credit Profile Changed
Sometimes a score changes even when there isn’t one obvious negative event.
Credit scores are calculated using information in your credit profile, and that information can change as lenders and creditors report updated account activity.
Balances change. Accounts age. New accounts appear. Inquiries are added. Older information may eventually stop being reported.
Different credit scoring models may also produce different scores, so the number you see from one source may not always match the score shown elsewhere.
Instead of focusing only on the number, look at the underlying information being reported. Understanding what changed can help you determine what to address next.
What Should You Do After Your Credit Score Drops?
Don’t panic or immediately apply for new credit.
Start by reviewing your overall credit situation and look for:
- Unexpected account changes
- Higher credit card balances
- Late payments
- New inquiries
- Collections or charge-offs
- Accounts you don’t recognize
- Potential reporting errors
If the information is accurate, focus on manageable steps such as making payments on time, reducing revolving balances when possible, and avoiding unnecessary new debt.
If you discover information that appears inaccurate or incomplete, further investigation or a dispute may be appropriate.
The goal shouldn’t be to chase a specific number overnight. Focus instead on understanding your credit profile and addressing the factors you can control.
Do You Need a Credit Repair Company?
Not every credit score drop requires professional credit repair services.
If the problem is simply higher credit card utilization, for example, the solution may involve managing and reducing your balances rather than disputing information on your credit reports.
Professional credit repair help may make more sense when you’re struggling to understand your reports, dealing with several potentially inaccurate accounts, or need assistance organizing and addressing credit-reporting issues.
A reputable credit repair company should explain what it can and cannot do without guaranteeing deletions, specific score increases, or loan approvals.
Credit improvement is a process, and the appropriate next step depends on what is actually being reported.
Get Help Understanding Your Credit
If your credit score dropped and you can’t determine why, Masters Credit Consultants can help you better understand the information appearing on your credit reports.
Our credit repair services focus on helping consumers review their credit information, identify potentially inaccurate or questionable reporting, and understand the next steps available to them.
Whether you’re trying to improve your credit, address possible credit report errors, or simply understand what may have caused a recent credit score drop, starting with accurate information can help you make more informed decisions.
Improving credit starts with understanding the problem—not chasing an overnight credit score fix.
Ready to take a closer look at your credit? Get started with Masters Credit Consultants today.
Why did my credit score suddenly drop?
A credit score may change because of higher reported balances, late payments, new inquiries, newly reported negative information, account changes, or other updates to your credit profile. Reviewing what recently changed can help you identify the possible cause.
Can high credit utilization lower my credit score?
Higher revolving credit utilization may negatively affect credit scores because scoring models can consider how much of your available revolving credit you’re using. Reducing balances may lower your utilization after creditors report the updated information.
Can a credit report error hurt my credit?
Potentially. If inaccurate information is included in the data used to calculate a credit score, it may affect your credit profile. Review questionable information carefully and dispute qualifying inaccuracies when appropriate.
Can credit repair increase my credit score?
Credit repair may help address potentially inaccurate or questionable information on your credit reports, but a legitimate credit repair company cannot guarantee a particular credit score increase or the removal of accurate negative information.
Should I hire a credit repair company if my score drops?
Not necessarily. First determine what caused the change. Professional credit repair services may be useful when you need assistance understanding complicated credit reports or addressing potentially inaccurate information.
How can I improve my credit after a score drop?
Start by identifying what changed. Depending on your situation, improving your credit may involve making payments on time, reducing credit card balances, limiting unnecessary credit applications, managing debt, or addressing inaccurate credit-report information.
🚀 Schedule Your Free Credit Consultation with Masters Credit Consultants
Schedule a free consultation with Masters Credit Consultants and discover how a personalized credit improvement strategy can help you achieve your financial goals.
Whether you’re preparing to buy a home, qualify for better financing, rebuild after financial hardship, or strengthen your business opportunities, taking action today could open the door to greater possibilities tomorrow.
📞 Phone: 1-844-620-8796
🌐 Website: https://www.masterscredit.com
📅 Schedule Your Free Consultation:
https://www.masterscredit.com/sign-up/
Additional Helpful Links
- Check Your Credit Before Buying a Home: What to Look for First
- What Does a Credit Repair Specialist Do? What to Know Before You Sign Up
- Can Bad Credit Make It Harder to Rent an Apartment? What to Check Before You Apply
- Tired of Credit Denials? How Credit Repair Services Can Help You Review What Lenders See
Related Questions
-
Why did my credit score suddenly drop?
-
How many points can a credit score drop at once?
-
Can high credit card balances cause my credit score to drop?
-
Will a late payment cause my credit score to drop?
-
Can a credit report error lower my credit score?
-
How can I improve my credit after my credit score drops?

Leave A Comment