
Kikoff and IdentityIQ: How They Can Support Your Credit Goals in 2026
Improving your credit is rarely about one quick fix.
For many consumers, progress comes from doing several things consistently: paying bills on time, establishing positive payment history, keeping an eye on credit reports, understanding what is affecting their credit, and catching potential problems before they become bigger issues.
That is where tools like Kikoff and IdentityIQ may fit into a broader credit strategy.
They serve different purposes.
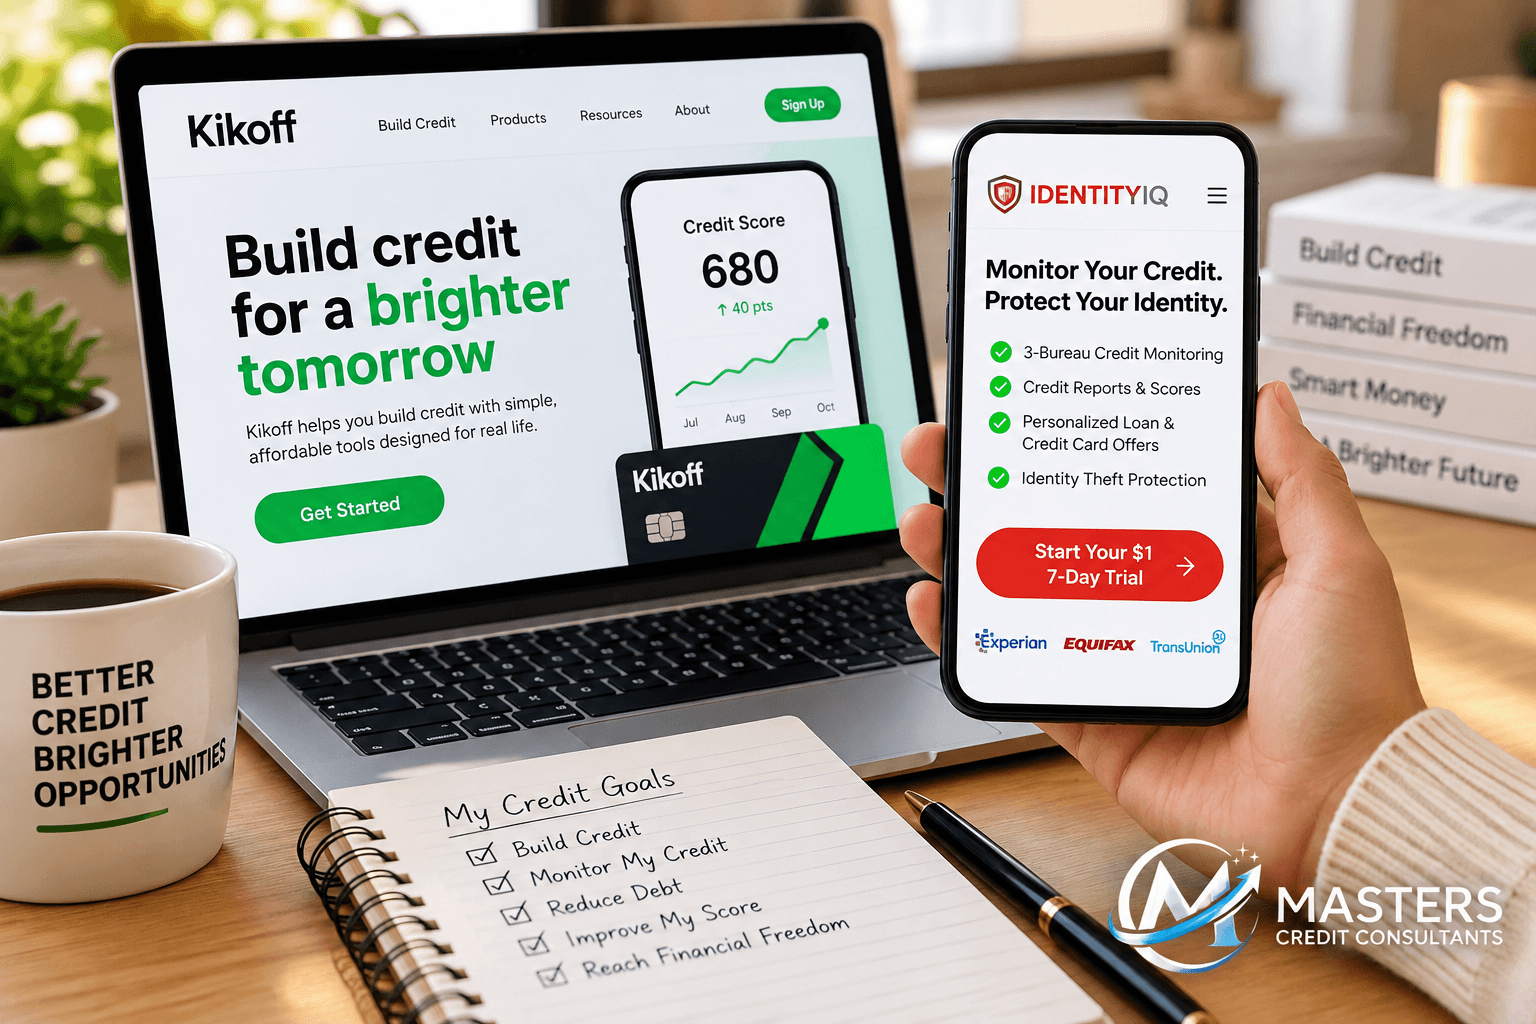
Kikoff offers tools designed to help consumers build and understand their credit profile, including its Credit Account, Financial Coach, Bill Reporting, and Rent Reporting.
IdentityIQ focuses heavily on credit monitoring and identity-related services, while also giving members access to credit reports and scores and personalized credit card and loan offers.
Neither service is a magic solution for your credit. But when used responsibly and alongside good financial habits, they can provide tools that support your larger credit goals.
Let’s look at how each one works.
Why Building Credit and Monitoring Credit Should Go Together
There are two sides to improving your credit profile:
Building positive credit activity and knowing what is being reported.
The Consumer Financial Protection Bureau (CFPB) explains that several factors can affect credit scores, including your payment history, the number and age of your accounts, how close you are to your credit limits, and recent credit activity.
The CFPB also emphasizes the importance of checking your credit reports for errors.
That means a good credit strategy should not focus only on your score.
You also want to understand:
- What accounts are appearing on your reports
- Whether payments are being reported accurately
- How much credit you are using
- Whether new accounts or inquiries appear
- Whether there are potential reporting errors
- How your financial habits are affecting your overall credit profile
Kikoff and IdentityIQ can support different parts of that process.
Kikoff: Building More Positive Credit Activity
Kikoff is primarily designed around credit building.
Its current platform includes several features that may be useful for consumers trying to establish or strengthen their credit history.
1. Kikoff Credit Account
One of Kikoff’s core products is its Credit Account.
Kikoff states that the account’s balance and monthly repayments are reported to Equifax, Experian, and TransUnion.
That matters because payment history is an important part of a consumer’s credit profile.
The CFPB recommends paying bills on time, every time, when working toward stronger credit. Positive payment history can remain on a credit report and contribute to establishing a stronger credit record over time.
With Kikoff, making your required payments on time can therefore add payment activity to your credit reports.
However, it is important to understand that opening a Kikoff account does not guarantee a particular credit score increase.
Your credit profile is influenced by multiple factors, and results will vary from person to person.
Interested in building additional credit history?
2. Kikoff Rent Reporting
Rent may be one of your largest monthly expenses, but traditionally, many renters have not received the same credit-building benefit from paying rent on time that homeowners receive from making mortgage payments.
Rent reporting is helping change that.
Kikoff currently offers Rent Reporting, which reports successful rental payments to Equifax and TransUnion. Kikoff also says eligible users can report up to two years of prior rental payments for an additional one-time fee.
This may be particularly useful for consumers with limited credit histories who already have a consistent record of paying rent.
The CFPB confirms that positive rental payment information can help consumers build credit and recommends that consumers interested in rent reporting investigate available programs and consider any associated fees.
Rent reporting does not guarantee a score increase, and not every credit scoring model or lender treats rental information in exactly the same way.
But it can potentially add another source of positive payment information to your credit profile.
3. Kikoff Bill Reporting
What about the bills you already pay every month?
Kikoff’s Bill Reporting feature allows eligible users to report certain recurring bills, including:
- Cell phone bills
- Electricity
- Natural gas
- Water
Kikoff currently states that these successful payments are reported to TransUnion monthly.
It also states that only successful payments are reported through this feature and that late payments are not reported through Bill Reporting.
For someone already paying these bills consistently, this can provide an opportunity to have some of that positive activity reflected in a credit file rather than leaving those payments completely outside the traditional credit-reporting system.
It is another example of using financial activity you already have as part of a broader credit-building strategy.
4. Fynn – Kikoff’s Financial Coach
Building credit becomes easier to understand when you know why your credit profile looks the way it does.
Kikoff now offers Fynn, an AI-powered Financial Coach.
According to Kikoff, Fynn provides personalized insights and actionable recommendations based on a user’s credit profile and goals.
That can help consumers move beyond simply checking a number.
Instead of asking only:
“What is my credit score?”
A more useful question may be:
“What factors in my credit profile should I be paying attention to?”
Understanding payment history, utilization, collections, account age, inquiries, and other credit factors can help you make more informed financial decisions.
How Kikoff May Support Your Credit Goals
Kikoff can potentially support several areas of a credit-building strategy at the same time.
Its Credit Account can establish reported payment activity with the three major credit bureaus.
Rent Reporting may allow qualifying rental payments to become part of your credit history with Equifax and TransUnion.
Bill Reporting can put eligible utility and phone payments to work by reporting successful payments to TransUnion.
And its Financial Coach can help users better understand the factors affecting their credit.
The important word is support.
Kikoff cannot erase accurate negative information, guarantee a particular credit score, or replace responsible financial habits.
Your overall credit profile still matters.
IdentityIQ: Know What’s Happening With Your Credit
Building credit is only one side of the equation.
You also need visibility.
If you’re actively working on your credit, you should know when information changes on your reports.
That is where a credit monitoring service such as IdentityIQ can be useful.
See Your Experian, Equifax and TransUnion™ Reports and Scores
Your credit information may not be identical across all three major credit bureaus.
A creditor may report information differently—or may not report an account to every bureau.
IdentityIQ provides access to credit information from Experian, Equifax and TransUnion™, with reports and scores that can be refreshed every 30 days under the applicable plan.
Having visibility across all three can help you develop a more complete picture of your credit profile.
For example, you might discover that:
- An account appears on only one or two reports
- Balances differ between reports
- An account status has changed
- A late payment is being reported
- A new inquiry has appeared
- Information has been updated following a dispute
The CFPB recommends reviewing credit reports regularly and checking them for inaccurate or incomplete information.
3-Bureau Daily Monitoring & Alerts
A lot can happen between the times you manually check your credit reports.
IdentityIQ offers 3-Bureau Daily Monitoring & Alerts under the applicable plan.
Credit monitoring can help alert you to certain changes involving your credit files.
That may be especially valuable if you are:
- Actively working on your credit
- Preparing to apply for a mortgage
- Planning to finance a vehicle
- Recovering from identity theft
- Watching the results of credit disputes
- Trying to keep closer track of changes to your reports
Monitoring does not prevent every form of identity theft or credit problem.
What it can provide is awareness.
The sooner you notice unexpected credit activity, the sooner you can investigate it.
IdentityIQ Now Goes Beyond Credit Monitoring
IdentityIQ can also be useful for consumers exploring their next financial steps.
In addition to monitoring and credit information, IdentityIQ now provides access to personalized loan and credit card offers.
This can make the platform useful beyond simply watching your reports.
However, personalized does not necessarily mean that an offer is the right financial choice for you or that approval is guaranteed.
Before applying for any new credit, consider:
- Interest rate
- Annual percentage rate (APR)
- Annual fees
- Other fees
- Repayment terms
- Credit limit
- Whether you actually need the account
- How an application could affect your credit
The CFPB advises consumers to apply only for credit they need because frequent applications for new credit can affect credit scores.
Use personalized offers as information to evaluate—not as a reason to open unnecessary accounts.
Try IdentityIQ for $1 for 7 Days
If you want to see what is being reported across your credit profile, IdentityIQ currently offers a $1 7-Day Trial through our link.
Start Your IdentityIQ $1 7-Day Trial
Before enrolling, review the current offer details, included features, pricing after the trial, and cancellation terms so you understand the service you are selecting.
Kikoff vs. IdentityIQ: What’s the Difference?
Although the two platforms overlap in some areas, we view their primary roles differently.
Kikoff is primarily a credit-building tool.
Its products can help establish credit activity and payment history, while features such as Rent Reporting and Bill Reporting may help consumers receive credit-reporting benefits from payments they are already making.
IdentityIQ is primarily useful for credit visibility and monitoring.
It can help consumers review information from the three major credit bureaus, monitor their credit files for changes, receive alerts, and explore personalized financial offers.
Think of it this way:
Kikoff can help you work on building your credit profile.
IdentityIQ can help you keep a closer eye on that profile.
For some consumers, using both types of tools can make sense as part of a broader credit strategy.
Tools Help—But Your Financial Habits Still Matter Most
No credit-building or monitoring service can replace the fundamentals.
The CFPB identifies paying bills on time as one of the most important steps consumers can take to improve their credit. It also recommends keeping credit balances manageable, maintaining established credit history, being thoughtful about opening new accounts, and regularly reviewing credit reports.
So whether you use Kikoff, IdentityIQ, both, or neither, continue focusing on the habits that matter:
Pay on time.
Keep balances under control.
Review your credit reports.
Dispute legitimate inaccuracies.
Avoid applying for credit you do not need.
Give positive credit history time to develop.
Credit improvement is usually a process, not an overnight event.
Build, Monitor and Understand Your Credit in 2026
The best credit tools are the ones you understand and use intentionally.
If your goal is to establish more positive credit activity, Kikoff may provide useful credit-building options through its Credit Account, Rent Reporting, Bill Reporting, and Financial Coach.
Explore Kikoff and Its Credit-Building Tools
If your goal is to gain greater visibility into what’s appearing across your credit files, IdentityIQ can provide access to Experian, Equifax and TransUnion™ credit information, monitoring and alerts, along with personalized loan and credit card offers.
Try IdentityIQ for $1 for 7 Days
And if you’re unsure how these tools fit into your overall credit strategy, Masters Credit Consultants can help you understand your credit profile and determine the next steps that make sense for your goals.
Visit the Masters Credit Consultants Homepage to learn more about our services.
Explore the Masters Credit Consultants Blog for more practical credit education and strategies.
Or Schedule a Free Credit Consultation to discuss your credit goals with our team.
Building credit gives you something to work toward. Monitoring credit helps you see what’s happening along the way. Understanding both can help you make more informed decisions in 2026.
🚀 Schedule Your Free Credit Consultation with Masters Credit Consultants
Schedule a free consultation with Masters Credit Consultants and discover how a personalized credit improvement strategy can help you achieve your financial goals.
Whether you’re preparing to buy a home, qualify for better financing, rebuild after financial hardship, or strengthen your business opportunities, taking action today could open the door to greater possibilities tomorrow.
📞 Phone: 1-844-620-8796
🌐 Website: https://www.masterscredit.com
📅 Schedule Your Free Consultation:
https://www.masterscredit.com/sign-up/
Additional Helpful Links
- Check Your Credit Before Buying a Home: What to Look for First
- What Does a Credit Repair Specialist Do? What to Know Before You Sign Up
- Can Bad Credit Make It Harder to Rent an Apartment? What to Check Before You Apply
- Tired of Credit Denials? How Credit Repair Services Can Help You Review What Lenders See
Related Questions
- What does it mean when a credit dispute comes back verified?
- Can I dispute an item again after it has been verified?
- Why did the credit bureau verify information I believe is inaccurate?
- What should I do if a verified account is still reporting incorrect information?
- How can I request the method of verification after a credit dispute?
- Can a credit repair company help if my credit dispute keeps coming back verified?

Leave A Comment