
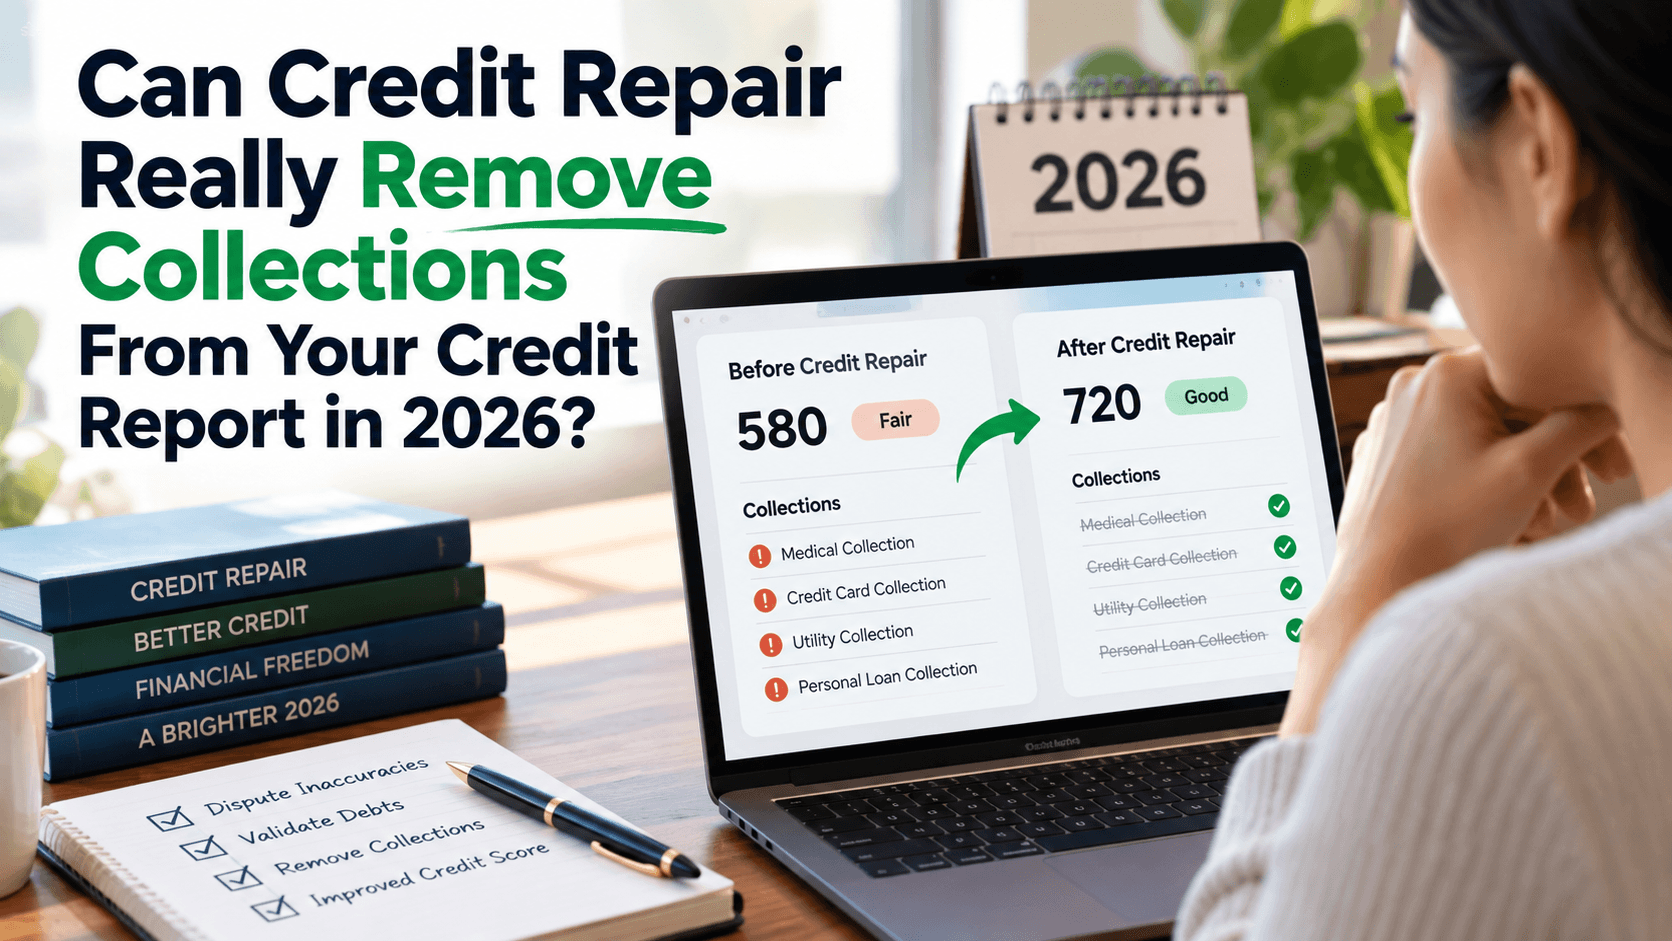
Can Credit Repair Really Remove Collections From Your Credit Report in 2026?
Seeing a collection account on your credit report can be frustrating, especially when you’re trying to qualify for a mortgage, finance a vehicle, or improve your financial standing. Even a single collection account can make lenders question your creditworthiness and potentially affect the interest rates you’re offered.
But here’s a question many consumers ask: Can credit repair really remove collections from your credit report?
The short answer is yes, in certain circumstances. Collection accounts that contain inaccurate, incomplete, outdated, or unverifiable information may qualify for correction or removal under federal credit reporting laws. However, accurate collection accounts generally cannot be removed simply because they negatively affect your credit score.
Understanding the difference is essential before you begin disputing accounts or paying collection agencies.
At Masters Credit Consultants, we believe that improving your credit starts with understanding what’s being reported, identifying potential inaccuracies, and developing a responsible strategy for moving forward.
In this guide, we’ll explain how collection accounts affect your credit, when they may be removed, what happens when you pay them, and how professional credit repair assistance can help you navigate the process.
Can Credit Repair Really Remove Collections?
Credit repair can help remove collection accounts when the information being reported violates applicable credit reporting requirements or cannot be verified through a reasonable investigation.
Under the Fair Credit Reporting Act (FCRA), consumers have the right to dispute information on their credit reports that they believe is inaccurate or incomplete.
When a dispute is submitted, credit reporting agencies generally must investigate the disputed information. If an item is found to be inaccurate, incomplete, or cannot be verified, it must be corrected or deleted as appropriate.
However, credit repair is not a legal loophole for removing every negative account.
A legitimate collection account that is accurate, complete, and within the permitted reporting period can generally remain on your credit report even after a dispute.
The goal of professional credit repair is to help ensure that the information being reported is accurate, properly documented, and compliant with applicable consumer protection laws.
Before starting the credit repair process, it’s important to understand exactly what appears on your credit reports.
Masters Credit Consultants recommends obtaining a copy of your 3-bureau credit report through IdentityIQ’s $1 7-Day Trial, which provides access to your credit reports, scores, monitoring alerts, and identity theft protection.
IdentityIQ offers access to credit information from Experian, Equifax, and TransUnion, with eligible reports and scores refreshable every 30 days.
Start Your IdentityIQ $1 7-Day Trial Here
The trial may convert to a paid subscription unless canceled. Review the current membership terms, pricing, and cancellation conditions before enrolling.
How Collection Accounts Affect Your Credit Score
A collection account typically appears when an unpaid debt is transferred or sold to a collection agency, although some creditors also manage collections internally.
Common examples include unpaid credit card balances, personal loans, utility bills, and certain medical debts.
Once a collection account is reported to a credit bureau, it may negatively affect your credit profile.
1. Collections Can Lower Your Credit Score
Payment history is an important factor in credit scoring. A collection account may indicate that a debt became seriously delinquent.
The exact impact depends on several factors, including:
- Your credit history before the collection appeared.
- The age of the collection account.
- The number of other negative accounts on your report.
- Whether the collection is paid or unpaid.
- The credit scoring model being used.
There is no universal number of points that a collection account will lower your score.
2. Collections May Affect Loan Approvals
Lenders may consider collection accounts when evaluating applications for mortgages, auto loans, personal loans, and credit cards.
Even when a collection account does not substantially affect a particular credit score, lenders may still consider the underlying debt and payment history.
3. Collections Can Make Borrowing More Expensive
A weaker credit profile may result in higher interest rates, less favorable loan terms, or additional underwriting requirements.
This is one reason why addressing credit reporting errors and developing positive credit habits can be important for your long-term financial goals.
4. Different Credit Scoring Models Treat Collections Differently
Not all credit scoring models evaluate collection accounts the same way.
For example, FICO Score 9 and the FICO Score 10 suite generally disregard qualifying paid third-party collections, while older scoring models may continue to consider them.
That means paying a collection account may affect one credit score differently from another.
When Can a Collection Be Removed From Your Credit Report?
Not every collection account qualifies for removal. However, certain reporting problems may provide legitimate grounds for a dispute.
1. The Collection Account Does Not Belong to You
If a collection account belongs to another person, it may have been reported because of mixed credit files, incorrect personal information, or identity theft.
You have the right to dispute accounts that are not yours.
2. The Collection Contains Incorrect Information
A collection account may contain errors involving the balance, account ownership, payment status, dates, or other identifying information.
If these details are inaccurate, they may need to be corrected. Removal may be appropriate when the account cannot be accurately verified.
3. The Same Debt Is Reported Incorrectly
A single debt may appear under both the original creditor and a collection agency without necessarily violating credit reporting laws.
However, inaccurate balances, duplicated collection entries, or inconsistent ownership information may warrant investigation.
4. The Collection Is Too Old to Be Reported
Most collection accounts can remain on a credit report for approximately seven years from the original delinquency that led to the collection.
If an account remains beyond the legally permitted reporting period, it may qualify for removal.
5. The Collection Cannot Be Verified
When you dispute an account, the credit reporting agency must conduct a reasonable investigation.
If the disputed information cannot be verified, the agency generally must delete or modify the information as required by law.
However, an account is not automatically removable merely because a consumer requests documentation or because the collection agency does not immediately respond directly to the consumer.
Important: A successful dispute may result in a correction rather than complete removal. The outcome depends on the specific reporting issue and investigation findings.
Can You Dispute a Collection That Is Accurate?
You can question information on your credit report, but disputing an account does not mean that an accurate collection must be removed.
Under the FCRA, consumers have the right to dispute information they reasonably believe is inaccurate or incomplete.
If an account is accurate, properly reported, and still within the permitted reporting period, the credit bureau may verify the information and leave it on your report.
Submitting repeated disputes without new information is not a reliable strategy for removing legitimate accounts.
Instead, focus on identifying actual reporting problems.
For example, an account may legitimately belong to you while still containing an incorrect balance, payment status, or delinquency date.
Those specific errors may be appropriate grounds for a dispute.
If you’ve already submitted a dispute and received a response stating that the account was verified, read our guide: My Credit Dispute Came Back Verified. Now What?.
You can also review the Consumer Financial Protection Bureau’s guidance on disputing credit report errors.
What Happens When You Pay Off a Collection?
Paying off a collection account can be a positive financial step, but it does not automatically remove the account from your credit report.
When a collection is paid, the account should generally be updated to reflect the appropriate payment status and remaining balance.
However, the collection history may remain visible until the applicable reporting period expires.
Will Paying Collections Improve Your Credit Score?
It depends on the scoring model and the rest of your credit profile.
Some newer scoring models disregard qualifying paid collection accounts, while others may continue to consider them.
As a result, paying a collection may improve your score, have little immediate effect, or produce a different result depending on the model.
Should You Pay a Collection Before Disputing It?
Before making a payment, consider confirming the debt’s ownership, accuracy, amount, and legal status.
If you believe the collection is incorrect, you may want to investigate the reporting issue first.
For older debts, it is also important to understand your state’s statute of limitations. In some states, making a payment or acknowledging a debt can affect the period during which a creditor or collector may sue to collect it.
What About Pay-for-Delete Agreements?
A pay-for-delete arrangement involves asking a collector to remove a collection entry in exchange for payment.
However, collection agencies are not required to agree to these requests, and accurate information generally should not be removed simply because payment was made.
Consumers should not assume that paying a collection will result in deletion.
The best approach depends on the account’s accuracy, age, legal status, and your broader financial situation.
How Long Do Collections Stay on Your Credit Report?
Most collection accounts may remain on your credit report for approximately seven years from the date of the original delinquency that led to the collection.
The reporting period generally does not restart when the debt is sold to another collection agency.
For example, if an account first became delinquent in March 2020 and was never brought current, the resulting collection would generally be expected to stop appearing around 2027, depending on the applicable reporting rules.
Paying the debt in 2026 does not ordinarily restart the federal credit reporting period.
It is also important to distinguish between the credit reporting period and the statute of limitations for filing a debt collection lawsuit. These are separate legal concepts.
Do Medical Collections Follow the Same Rules?
Medical collections receive different treatment under the nationwide credit reporting agencies’ reporting policies.
Under those policies, paid medical collections, medical collections with an initial reported balance below $500, and medical collections less than one year old are generally excluded from consumer credit reports.
Unpaid medical collections that meet the applicable reporting criteria may still appear.
Consumers should review the specific information being reported rather than assume that every medical collection qualifies for removal.
Common Mistakes People Make When Disputing Collections
Trying to remove collections without understanding the process can create unnecessary delays and frustration.
Here are some common mistakes to avoid.
1. Disputing Every Negative Account Without Evidence
A negative account is not necessarily an inaccurate account.
Disputes should identify a genuine concern, such as an incorrect balance, account ownership issue, or reporting date.
2. Using Generic Credit Dispute Templates
Generic dispute letters may not adequately explain the specific reporting error.
A stronger dispute identifies the account, explains the issue clearly, and includes supporting documentation when available.
Read our related article: Do Online Credit Dispute Letter Templates Really Work?
3. Ignoring All Three Credit Bureaus
An account may appear differently on your Experian, Equifax, and TransUnion reports.
Reviewing all three can help identify inconsistencies that may otherwise go unnoticed.
Masters Credit Consultants recommends obtaining a copy of your 3-bureau credit report through IdentityIQ’s $1 7-Day Trial, which provides access to your credit reports, scores, monitoring alerts, and identity theft protection.
Experian, Equifax, and TransUnion reports and scores can be refreshed every 30 days under eligible IdentityIQ plans.
Review Your 3-Bureau Credit Reports With IdentityIQ
Review the trial and ongoing subscription terms before signing up.
4. Failing to Keep Documentation
Always retain copies of dispute letters, supporting documents, credit bureau responses, and relevant communications with creditors or collection agencies.
Documentation may become important if an error remains unresolved.
5. Expecting Instant Results
Credit reporting disputes generally take approximately 30 days to investigate, although certain circumstances may extend the process.
Complex cases or disputes involving multiple accounts may require additional follow-up.
6. Focusing Only on Removing Negative Accounts
Removing inaccurate information is only one part of improving your credit profile.
Consistent on-time payments, responsible credit utilization, and maintaining healthy financial habits can also support your long-term credit goals.
How Professional Credit Repair Services Can Help
Handling multiple collection accounts can feel overwhelming, particularly when information differs across credit bureaus or previous disputes have not resolved the problem.
Professional credit repair assistance can help consumers organize their credit information and understand the steps available to address potential inaccuracies.
At Masters Credit Consultants, our approach emphasizes reviewing credit reports, identifying potential reporting concerns, and helping clients work toward stronger financial habits.
1. Reviewing Credit Report Information
The first step is understanding what is being reported and identifying accounts that may require closer examination.
This includes reviewing collection balances, account dates, payment statuses, and other reported details.
2. Identifying Potential Reporting Errors
Not every negative account qualifies for removal.
A careful review helps distinguish potentially inaccurate information from legitimate negative history.
3. Assisting With the Dispute Process
When appropriate, professional assistance can help consumers prepare organized, account-specific disputes supported by relevant information.
Consumers also have the right to submit these disputes directly to credit bureaus and furnishers at no cost.
4. Developing a Long-Term Credit Improvement Strategy
Improving your credit is not only about resolving past reporting problems.
It also involves building positive financial habits that support future borrowing opportunities.
Can Kikoff Help You Build Credit While Addressing Collections?
While you’re working to resolve collection account issues, you may also want to explore tools designed to help establish positive payment history.
Kikoff offers credit-building products and financial tools that may help eligible consumers develop more consistent credit habits.
Depending on the product and eligibility, Kikoff’s features may include credit-building accounts, payment reporting options, and tools for monitoring financial progress.
However, Kikoff does not automatically remove collection accounts or erase accurate negative information.
Its potential value is in supporting positive credit-building activity alongside a responsible strategy for addressing existing credit concerns.
Explore Kikoff Credit-Building Tools
Review Kikoff’s current product terms, fees, eligibility requirements, and credit reporting details before enrolling. Credit score improvements are not guaranteed.
Frequently Asked Questions
Can credit repair remove collections from my credit report?
Yes, when collection accounts contain inaccurate, incomplete, outdated, or unverifiable information that requires correction or deletion under applicable law. Accurate collection accounts generally cannot be removed simply because they are negative.
Can I remove collections without paying them?
Potentially. If a collection account is inaccurate, does not belong to you, or is too old to be reported, you may have grounds to dispute it without paying. However, disputing a credit report entry does not automatically eliminate a legally valid debt.
Will my credit score increase if a collection is removed?
It may. The impact depends on your overall credit profile, the age of the collection, and the credit scoring model. No specific score increase can be guaranteed.
Does paying off a collection remove it from my credit report?
No. Paying a collection generally updates its payment status, but the account may remain on your credit report until the applicable reporting period expires.
Can a collection agency report the same debt twice?
A debt may legitimately appear under both the original creditor and a collection agency. However, duplicate collection entries or inaccurate balances may warrant investigation.
How long does a credit dispute take?
Credit reporting agencies generally have 30 days to investigate a dispute, with extensions permitted in certain circumstances. More complex credit repair efforts may involve multiple disputes and follow-up actions.
Can a collection account come back after being removed?
In certain circumstances, previously deleted information may be reinserted if the legal requirements for reinsertion are satisfied, including appropriate certification and consumer notification.
Is professional credit repair worth it?
Professional credit repair assistance may be useful if you have multiple accounts to review, complicated reporting issues, or limited time to manage disputes yourself. However, consumers can dispute inaccurate credit reporting information on their own for free, and no company can guarantee the removal of accurate negative information.
Should I use IdentityIQ before starting credit repair?
Reviewing your credit reports can help you understand which accounts are being reported and identify potential errors.
IdentityIQ provides access to three-bureau credit information, monitoring features, and identity protection services under eligible plans.
You can explore the IdentityIQ $1 7-Day Trial, subject to current enrollment and subscription terms.
Get a Free Credit Analysis With Masters Credit Consultants
Collection accounts can affect more than just your credit score. They may influence your ability to qualify for financing, obtain favorable borrowing terms, and move forward with important financial goals.
But having collections on your credit report does not mean you have to remain uncertain about your options.
The first step is understanding which accounts are accurate, which may contain reporting errors, and what actions may be appropriate for your situation.
At Masters Credit Consultants, we help consumers better understand their credit challenges and explore responsible strategies for addressing credit reporting concerns.
Whether you’re dealing with collection accounts, disputed information, or other negative items, getting professional guidance can help you approach the process with greater clarity.
Ready to Take the First Step Toward Better Credit?
SCHEDULE YOUR FREE CREDIT CONSULTATION
You can also GET STARTED TODAY and explore your options with Masters Credit Consultants.
Your credit history doesn’t have to define your financial future. Start by understanding your options today.
🚀 Schedule Your Free Credit Consultation with Masters Credit Consultants
Schedule a free consultation with Masters Credit Consultants and discover how a personalized credit improvement strategy can help you achieve your financial goals.
Whether you’re preparing to buy a home, qualify for better financing, rebuild after financial hardship, or strengthen your business opportunities, taking action today could open the door to greater possibilities tomorrow.
📞 Phone: 1-844-620-8796
🌐 Website: https://www.masterscredit.com
📅 Schedule Your Free Consultation:
https://www.masterscredit.com/sign-up/
Additional Helpful Links
- Check Your Credit Before Buying a Home: What to Look for First
- What Does a Credit Repair Specialist Do? What to Know Before You Sign Up
- Can Bad Credit Make It Harder to Rent an Apartment? What to Check Before You Apply
- Tired of Credit Denials? How Credit Repair Services Can Help You Review What Lenders See
Related Questions
- Can credit repair companies legally remove collection accounts from your credit report in 2026?
- How long does it take to remove collections from your credit report through credit repair?
- Can you remove a paid collection from your credit report, or does it stay for seven years?
- What types of collection accounts can be disputed and removed from your credit report?
- Will removing collections from your credit report improve your credit score in 2026?
- What should you do if a collection account remains on your credit report after a dispute?

Leave A Comment